Shionogi & Co. has announced that it will make IntraBio, a US biopharmaceutical company, a wholly owned subsidiary for approximately 31.56 billion yen. Behind this move are concerns over declining revenues due to the patent expiration of its mainstay HIV drugs and a strategic aim to foster the rare disease field as a new pillar of growth.
- Acquires US-based IntraBio as a wholly owned subsidiary for 2 billion US dollars
- The rights to AQNEURSA, a rare neurological disease drug that serves as the centerpiece of the acquisition
- The Issue of HIV Drug Patent Expiration and the Acceleration of Business Restructuring
- Three Major M&As Involving Over ¥880 Billion and the Establishment of the Rare Disease Business
- Concerns over Deteriorating Financial Health and Stock Market Trends
- Challenges in the Integration Process and Medium-to-Long-Term Points of Focus
Acquires US-based IntraBio as a wholly owned subsidiary for 2 billion US dollars
On October 5, 2026, Shionogi & Co., Ltd. announced at its Board of Directors meeting that it has entered into a definitive agreement to acquire U.S. biopharmaceutical company IntraBio Inc. as a wholly owned subsidiary through its U.S. group company, Shionogi Inc. The acquisition price is 2.0 billion U.S. dollars (approximately 315.56 billion yen, calculated at an exchange rate of 157.78 yen per U.S. dollar), with plans to acquire all outstanding shares for cash. The completion of this transaction is subject to approvals from regulatory authorities in relevant countries and is scheduled for November to December 2026. Established in 2015 and headquartered in Austin, Texas, IntraBio is a company specializing in the research and development of small-molecule drugs for rare neurodegenerative and inherited neurological diseases. For the fiscal year ended December 2025, the company reported net sales of approximately 67.867 million U.S. dollars, an operating loss of approximately 35.292 million U.S. dollars, and consolidated net assets of approximately 144.549 million U.S. dollars. By investing a valuation of approximately 14 times its net assets, Shionogi will integrally acquire IntraBio’s intellectual property, marketing rights, and specialized personnel. Please refer to the diagram below for an overview of this acquisition.
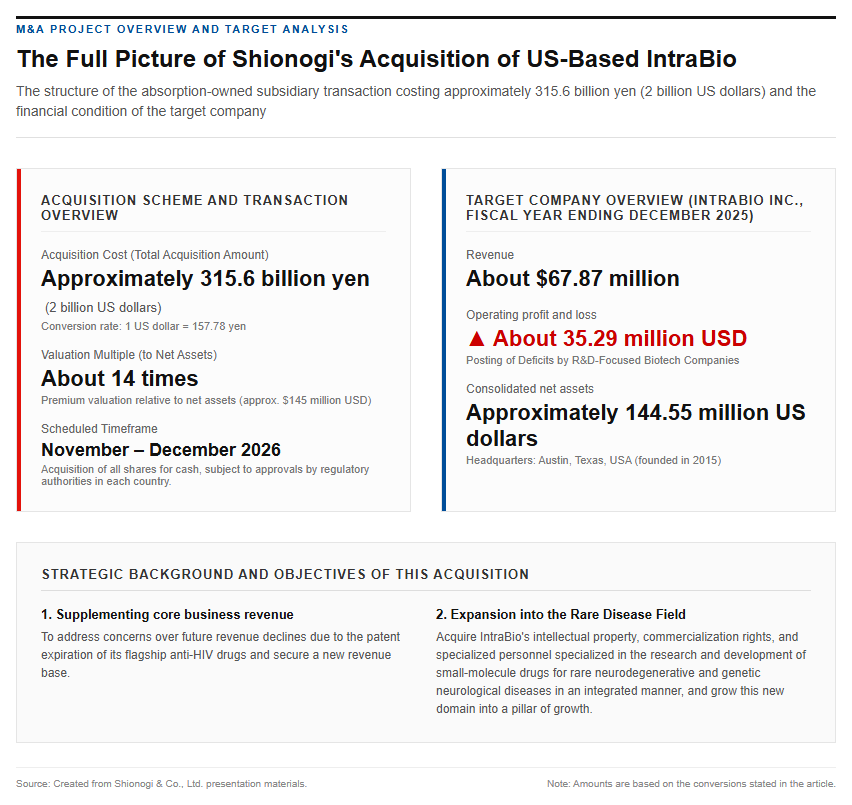
With this major deal, Shionogi & Co. aims to dramatically expand its business foundation in the rare disease market.
The rights to AQNEURSA, a rare neurological disease drug that serves as the centerpiece of the acquisition
The primary objective of this acquisition is to secure all global rights to “AQNEURSA” (generic name: levacetylleucine), a therapeutic drug developed by IntraBio, along with its related compounds. The drug has already received approval and been launched in the U.S. and Europe as a treatment for neurological symptoms associated with Niemann-Pick disease type C (NPC), a designated intractable lysosomal storage disorder that affects approximately 1 in 100,000 people. Furthermore, on September 18, 2026, it received approval for an additional indication from the U.S. Food and Drug Administration (FDA) as the world’s first and only treatment for ataxia-telangiectasia (A-T), a condition that manifests in early childhood and causes movement disorders and other symptoms. Applications for similar indication expansions are also underway in Europe. Currently, no other FDA-approved drugs exist for A-T, representing an extremely high unmet medical need. By securing the rights to this drug alongside its existing portfolio, Shionogi will dramatically strengthen its pipeline in the field of rare neurological diseases. In addition, the company plans to accelerate its in-house R&D efforts—such as the Fragile X syndrome treatment zatolmilast, Jordan’s syndrome, and Pompe disease treatments—by integrating IntraBio’s advanced expertise.
The Background of Massive Investment and Shionogi & Co.’s Business Strategy
The Issue of HIV Drug Patent Expiration and the Acceleration of Business Restructuring
Behind Shionogi & Co., Ltd.’s successive massive investments lies the patent cliff issue concerning its largest revenue source, anti-HIV drugs. Royalty income from the anti-HIV drug dolutegravir accounts for approximately half of the company’s revenue, but with the expiration of its core patents approaching, countermeasures against future revenue declines have become an urgent task. Chairman, President, and CEO Isao Teshirogi has publicly stated from an early stage that the company would reform its business structure through external investments to avoid overpaying for acquisitions rushed right before the patent expiration. The company’s financial results in terms of net sales and operating profit continue to hit record highs, prompting a decision to take risks and build a new foundation for growth while ample funds are on hand. In addition, its domestic ethical pharmaceuticals business faces the challenge where the performance of the infectious disease domain—such as the influenza treatment Xofluza and the COVID-19 treatment Xocova—is easily swayed by outbreak conditions. Please refer to the graph below for the transition of the product portfolio.
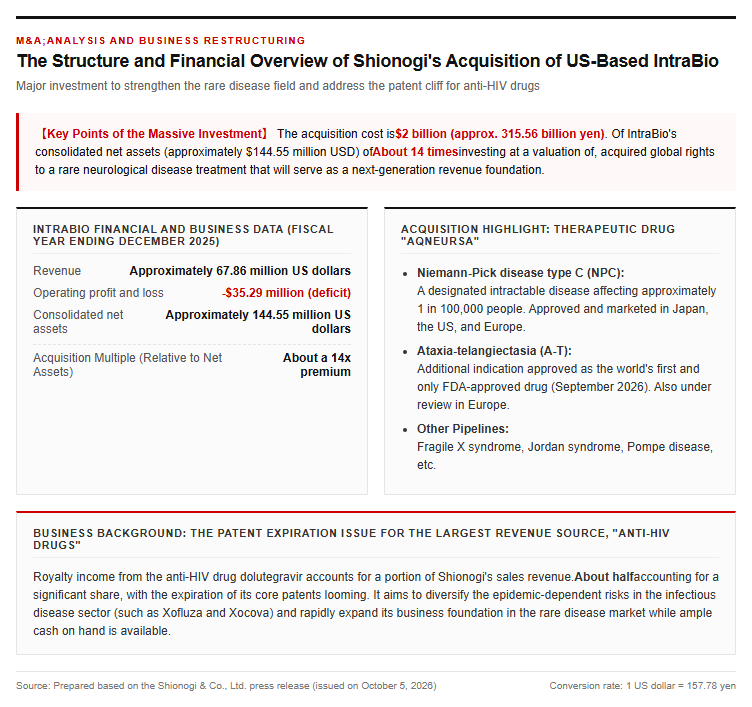
Going forward, the company aims to stabilize its business by increasing the proportion of rare disease and QOL (quality of life) disease areas, which are less susceptible to patent expirations, and keeping the share of infectious diseases below 20% in the future.
Three Major M&As Involving Over ¥880 Billion and the Establishment of the Rare Disease Business
Shionogi carried out a series of large-scale deals exceeding a total of 880 billion yen from fiscal 2025 to fiscal 2026. Key initiatives are as follows.
- Strengthening of domestic sales networks and research systems through the acquisition of Torii Pharmaceutical and the pharmaceutical business of the Japan Tobacco (JT) Group
- Acquired the amyotrophic lateral sclerosis (ALS) treatment edaravone (US product name Radicava) business from Tanabe Pharma for $2.5 billion (approx. 390 billion yen)
- Conversion of UK-based ViiV Healthcare into an Equity-Method Affiliate through Additional Investment and Enhanced Influence
In particular, in the U.S. Radicava business, where the business transfer was completed in April 2026, a specialized team of 143 people has begun operations. Edaravone’s overseas sales reached the 100 billion yen scale for the fiscal year ended March 2025, establishing a strong rare disease sales infrastructure in the United States. By adding IntraBio’s AQNEURSA, which is being acquired, to this Radicava sales infrastructure, it is possible to enhance the productivity of the sales organization while eliminating the risk of single-product dependency. Shionogi & Co., Ltd. expects to upwardly revise its revenue target of 800 billion yen for fiscal year 2030, and is poised to establish its global rare disease business, centered around the U.S., as a new growth pillar.
Stock Market Reaction and Future Growth Roadmap
Concerns over Deteriorating Financial Health and Stock Market Trends
In the stock market, a decline in share prices was observed immediately following the announcement of the acquisition of IntraBio. On the afternoon of October 5, 2026, in the Tokyo stock market, Shionogi & Co.’s share price expanded its losses heading into the afternoon session. This was because concerns spread among market participants over potential financial deterioration resulting from paying a massive acquisition consideration of approximately 315.6 billion yen for a company whose recent financial performance showed an operating loss and whose consolidated net assets were approximately $144,549,000 USD. On the other hand, analysts’ medium-to-long-term earnings forecasts remain relatively solid. In the first-quarter financial results announced in August 2026, net sales reached 163.0 billion yen, beating expectations by approximately 2.9%, and earnings per share (EPS) also yielded strong results that significantly exceeded forecasts. Analyst consensus forecasts project net sales for 2027 to be 699.8 billion yen, predicting a growth pace that exceeds the industry average. The average target price has also been maintained around the 3,404 yen level, indicating that while the financial burden of the massive investment is being felt in the short term, the potential for earnings expansion through the acquisition of new drugs is being calmly evaluated over the long term.
Challenges in the Integration Process and Medium-to-Long-Term Points of Focus
In future developments, the most anticipated aspects are PMI (Post-Merger Integration) following the completion of the acquisition and the speed of new drug sales growth. The complete acquisition of IntraBio is scheduled to be finalized between November and December 2026, and the impact on consolidated financial results for the fiscal year ending March 2027 is currently under review. The ultimate keys to the success of return on investment are market development for AQNEURSA—which has just been approved in the U.S.—for the A-T indication, and the status of obtaining additional indication approvals in Europe. In addition, goodwill and intangible assets have surged due to the large-scale acquisitions carried out in rapid succession (JT’s pharmaceutical business, Mitsubishi Tanabe Pharma’s edaravone business, and IntraBio), making appropriate management of impairment risk an important challenge. Given that Shionogi has a history of recording impairment losses on past U.S. corporate acquisitions, its execution capabilities in steadily generating cash flow from the acquired assets will be put to the test. Building on this series of business restructuring efforts, the company plans to announce a new medium-term management plan for fiscal 2027 and beyond. Close attention is being paid to whether the widespread adoption of new drugs and the progress of its in-house development pipeline will contribute to future sustainable growth and the enhancement of corporate value.
Reference Page
- [Notice Regarding the Acquisition of US-based IntraBio Inc. as a Wholly Owned Subsidiary – Shionogi & Co., Ltd.] https://www.shionogi.com/jp/ja/news/2026/10/20261005_02.html
【#Shionogi #MandA #Biotechnology #Pharmaceuticals #RareDiseases #InvestmentStrategy #DrugDevelopment】
コメント