
Elan Corporation, which develops services for medical and nursing care facilities, has upwardly revised its consolidated ordinary profit forecast for the fiscal year ending December 2026 by 15.0% from the previous forecast to 5.75 billion yen. This was driven by the fact that subscription applications for its core “CS Set” service at adopting facilities have performed solidly above expectations, in addition to significant contributions from the control of SG&A expenses and the recording of operating gains from investment business partnerships.
- Raises full-year ordinary profit forecast to 5.75 billion yen, marking a record high
- Factors Behind Steady Contract Trends for CS Sets and the Recording of Extraordinary Losses
- A Flat-Rate Package for Healthcare and Nursing Care Enabling “Hands-Free Hospital Admissions”
- The Platform Structure of the Three-Way Partnership and Measures Supporting High Profit Margins
- The 80 Billion Yen Sales Target in the New Medium-Term Management Plan and Overseas Expansion
- Evaluation of Synergy with Parent Company M3 and the Introduction of Shareholder Benefits
Raises full-year ordinary profit forecast to 5.75 billion yen, marking a record high
On November 20, 2026, TSE Prime-listed ELAN Corporation announced a revision to its full-year consolidated financial forecasts for the fiscal year ending December 2026. While the previous announcement projected full-year consolidated ordinary profit at 5.0 billion yen, the latest revision upwardly revised this by 15.0% to 5.75 billion yen. Compared to the previous fiscal year’s result of 4.18 billion yen, the profit growth rate expands significantly to a 37.4% increase, further boosting the previously forecasted record-high profit. In the estimated consolidated ordinary profit for the second half (July–December 2026), it was also increased by 31.1% from the previous forecast of 2.4 billion yen to 3.15 billion yen, with the profit growth rate projected to rapidly expand to 46.8% year-on-year. In conjunction with this announcement, interest in the steady expansion of business performance is also growing in the stock market. Regarding the earnings trends and key metric movements explained in this article, please also refer to the following visual summary.
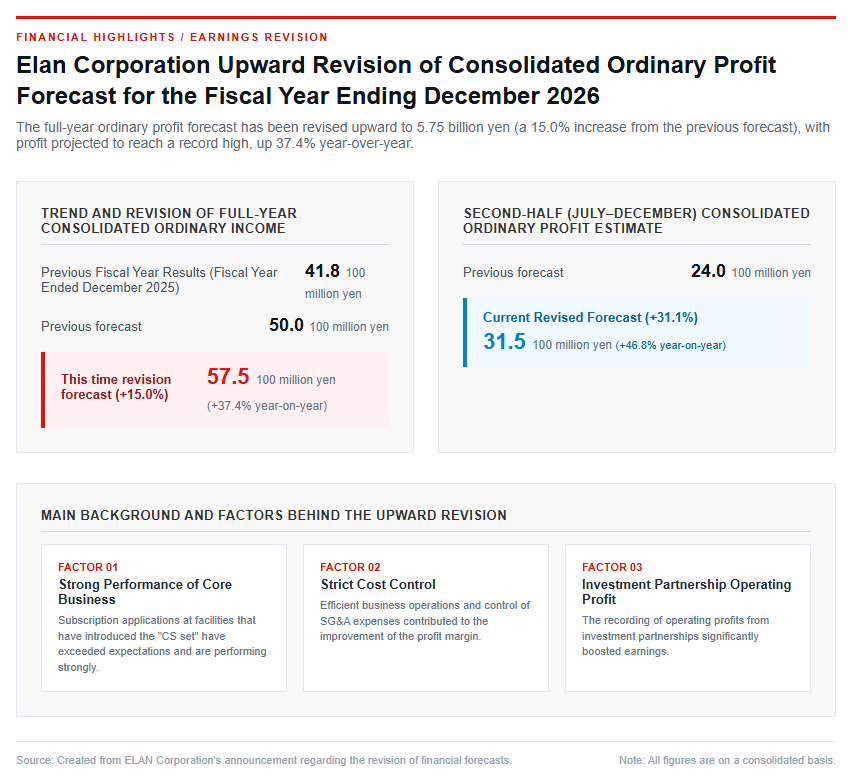
.
Factors Behind Steady Contract Trends for CS Sets and the Recording of Extraordinary Losses
The primary factor behind the recent upward revision of the earnings forecast was the steady trend in usage applications across facilities that have already introduced the core “CS Set” business. Operating profit was boosted as selling, general, and administrative expenses remained below initial projections alongside the expansion of net sales, and the recording of gains on investment business partnerships further contributed to the upward deviation in ordinary profit. Meanwhile, net income attributable to owners of the parent was downwardly revised by 53.1% from the previous forecast of 3.2 billion yen to 1.5 billion yen, and is expected to decrease by 45.8% compared to the previous fiscal year. The background to the decrease in net income includes the recording of valuation losses on investment securities held by the company, as well as the recording of impairment losses on goodwill and other items related to consolidated subsidiaries as extraordinary losses. The following figure summarizes the contrasting factors of revenue expansion in the core business and the occurrence of extraordinary losses.
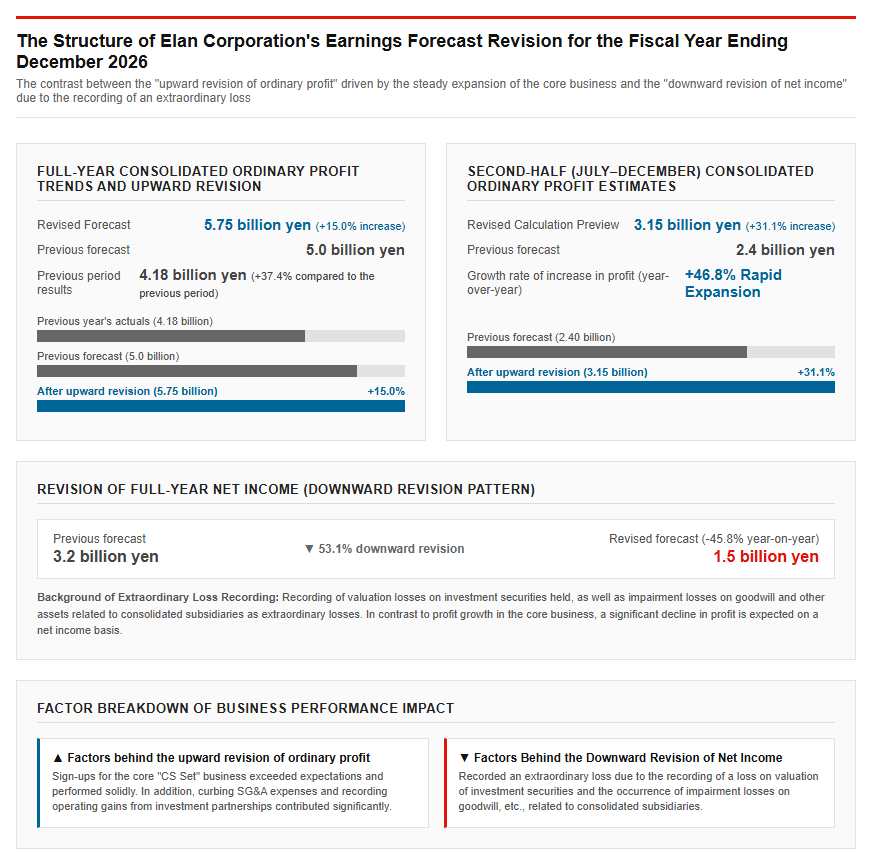
.
Strengths and Revenue Structure of Elan’s Unique Business Model, the “CS Set”
A Flat-Rate Package for Healthcare and Nursing Care Enabling “Hands-Free Hospital Admissions”
Elan Corporation’s core business, the “CS (Care Support) Set,” is a flat-rate service that provides hospital inpatients and nursing care facility residents with a package of clothing and towel rentals including laundry, as well as daily personal items. Users can utilize the service under a daily flat-rate pricing structure (ranging from about 300 to 700 yen per day), which eliminates the hassle of preparing necessary items for hospitalization, visits, or discharge, enabling “hands-free hospitalization and visits.” For the facilities, nurses and care workers are freed from incidental tasks such as supplying items and arranging laundry, creating an environment where they can concentrate on their primary professional duties. Furthermore, because the company directly handles invoice mailing and customer inquiries for the users, the structure is designed to prevent uncollected payment risks and significantly reduce administrative burdens.
The Platform Structure of the Three-Way Partnership and Measures Supporting High Profit Margins
Elan’s business model is built on a collaborative relationship that brings benefits to three parties: users, hospitals/nursing care facilities, and local linen supply businesses in the region. For hospitals and facilities, it provides a new revenue source by paying commissions for the outsourcing of reception administration, while creating new demand for existing contracted linen providers in the form of daily necessities sales opportunities and clothing rental operations. The company functions as a sort of platformer that oversees these elements, having established a system that increases procurement and logistics efficiency as the number of contracted facilities grows. In addition, changing the accounting treatment for its proprietary, in-house-developed patient gown “lifte” from lump-sum depreciation to a three-year straight-line depreciation method has leveled out one-time implementation costs, significantly contributing to the improvement of gross profit and operating profit margins. Please refer to the structural diagram below for details on the service delivery flow.
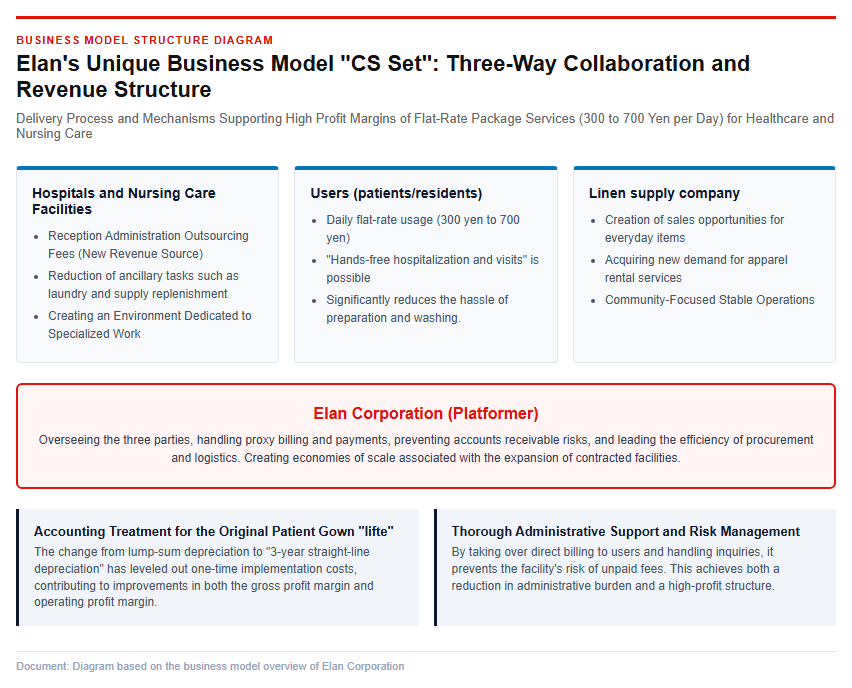
.
Medium- to Long-Term Growth Strategy and Future Outlook for Shareholder Returns
The 80 Billion Yen Sales Target in the New Medium-Term Management Plan and Overseas Expansion
Elan is promoting a new medium-term management plan covering the three-year period from 2026 to 2028. By the final year of 2028, the company aims to achieve consolidated net sales of 80 billion yen (compared to 55.4 billion yen actuals in 2025), consolidated operating profit of 7.5 billion yen (compared to 4.2 billion yen in the same period), and an operating profit margin of 9.4%, while setting a lower limit target of 25.0% for ROE as an indicator of capital efficiency. Out of the 16.0 billion yen in operating cash flow to be generated during the period, the company has formulated a capital allocation plan to direct between 9.0 billion and 12.0 billion yen toward domestic and international M&A and business investments. In its overseas operations, Elan has made GREEN and TMC—providers of laundry services for major hospitals in Vietnam, where aging populations and medical demand are growing—into consolidated subsidiaries, thereby strengthening its business foundation in the region.
Evaluation of Synergy with Parent Company M3 and the Introduction of Shareholder Benefits
Collaboration with M3, its parent company that acquired a 55.0% stake through a tender offer (TOB) in 2024, is also a major factor that will accelerate future growth. Sales approaches leveraging M3’s network of medical institutions are expected to improve the speed of new CS set adoptions. Additionally, as part of its shareholder return policy, the introduction of a new shareholder benefit program was announced on November 19, 2026. The program offers 5,000 yen worth of digital gifts to shareholders holding 300 or more shares for one year or longer as of the end of December each year, with a special exception applying only for the end of December 2026, the first year of introduction, where the continuous holding period requirement is waived. The establishment of this benefit program and the annual dividend forecast of 16 yen were highly praised by individual investors, serving as a positive catalyst for a rebound in the company’s stock price in the stock market immediately following the announcement.
Reference Page
【#Elan #UpwardEarningsRevision #CSSet #HandsFreeHospitalization #StockInvestment】

コメント